Business/Investment
CBN Questions Regulatory Gap as ‘Pay Small Small’ Credit Expands Beyond Nigerian Banks
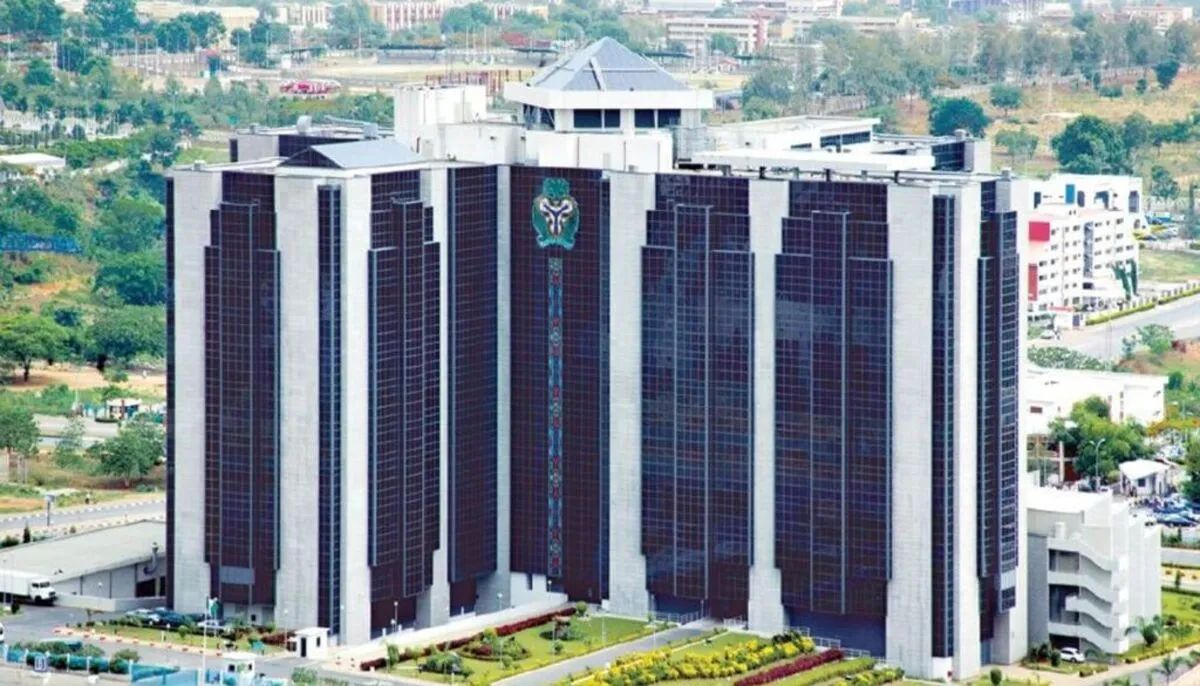
The Central Bank of Nigeria has drawn attention to an emerging regulatory challenge in the country's rapidly changing financial sector as more businesses outside traditional banking allow customers to spread payments for goods and services over time.
The issue centres on the increasingly popular “pay small small” model, broadly associated with instalment payments and Buy Now, Pay Later arrangements, which allow consumers to obtain products or services while settling their obligations gradually.
CBN Governor Olayemi Cardoso raised the issue through Abiodun Olalekan Okunola, Head of the apex bank's Innovation Management Division, during Nigeria Fintech Week 2026 in Lagos.
The remarks indicate that the CBN is examining how existing regulatory structures should respond as financial services become increasingly integrated into businesses that are not conventional banks or financial institutions.
Embedded Finance Creates New Regulatory Questions
At the heart of the debate is “embedded finance,” where financial products such as payments, insurance or credit are integrated into platforms whose primary businesses may lie outside the financial sector.
The model has become increasingly visible as technology allows companies to incorporate payment and financing options directly into customers' purchasing journeys.
Cardoso's representative pointed to travel businesses Air Peace and Wakanow as examples where consumers may encounter options that allow them to spread payments.
The CBN's concern is not simply that customers are paying in instalments. The regulatory question is whether particular arrangements constitute the provision of credit and, if they do, which regulator should supervise companies offering them when those businesses are not themselves licensed as traditional credit institutions.
That distinction could become increasingly important as the boundaries separating financial institutions, technology companies, retailers and service providers become less obvious.
**Consumer Protection Is Part of the Concern
**
Consumer protection was another major issue raised during the discussion.
Traditional financial institutions operate within established regulatory frameworks that provide channels through which customers can make complaints and seek redress.
But difficulties may arise when a consumer obtains what effectively functions as credit through a company outside the conventional financial system.
Cardoso questioned how the CBN should respond when customers bring complaints concerning such businesses if the companies involved are not licensed or supervised by the central bank.
The concern highlights a broader challenge confronting regulators around the world: technological innovation can produce financial products faster than traditional regulatory categories evolve.
The CBN has not, however, announced a ban on instalment-payment arrangements based on the remarks reported from Nigeria Fintech Week. Rather, the comments raise questions about licensing, supervision and responsibility for protecting consumers when non-bank businesses participate in credit-related activities.
Nigeria's Digital Credit Market Continues to Expand
The regulatory discussion comes as digital lending and Buy Now, Pay Later services continue to develop in Nigeria.
Nairametrics, citing earlier market research, reported that Nigeria's Buy Now, Pay Later market had been projected to expand from about $1.42 billion in 2024 to approximately $2.61 billion by 2030.
Travel is one sector where such payment arrangements have gained attention.
In 2025, Kalabash, a fintech subsidiary of Wakanow Group, partnered with Outpayce, the payments business of travel-technology company Amadeus, to expand the availability of its instalment-based travel payment solution.
The appeal to consumers is straightforward: instead of paying the entire cost of certain purchases immediately, eligible customers can distribute payments over an agreed period.
For businesses, embedded financial services can potentially make expensive products or services accessible to a broader range of customers.
However, once an arrangement moves from simply accepting payments into extending credit, regulators face questions over licensing, disclosure requirements, consumer rights, responsible lending and dispute resolution.
FCCPC Also Plays a Role in Digital Lending Oversight
Nigeria's regulatory landscape for digital credit extends beyond the CBN.
The Federal Competition and Consumer Protection Commission has been heavily involved in oversight of non-bank digital lenders, particularly following complaints about privacy violations and aggressive debt-recovery practices in the sector.
The FCCPC introduced the Digital, Electronic, Online or Non-Traditional Consumer Lending Regulations 2025 to establish standards relating to areas including consumer protection, transparency and data handling.
The regulatory situation has nevertheless faced legal complications.
In May 2026, the FCCPC announced that it had suspended implementation and enforcement of the DEON Regulations in compliance with an interim order issued by the Federal High Court in Lagos. The commission said at the time that it intended to challenge the order and the underlying lawsuit.
This means the regulatory environment surrounding digital and non-traditional lending should not be presented as a simple matter of one agency imposing a new rule. Different laws, regulators, licensing arrangements and ongoing legal developments can affect particular business models.
Financial Innovation Is Testing Traditional Boundaries
The debate surrounding “pay small small” products reflects a much wider transformation of Nigeria's financial system.
At Nigeria Fintech Week, the CBN identified embedded finance alongside areas such as artificial intelligence, open banking, digital money and cross-border commerce as developments reshaping financial services.
The central bank has also acknowledged the wider challenge of regulatory fragmentation as financial technology companies expand into activities traditionally supervised by different agencies.
A modern digital platform could potentially combine payments, lending, insurance and other services within a single customer experience, while those activities may fall under different regulators.
For consumers, these innovations can mean greater convenience and more payment choices.
For regulators, however, they create an increasingly important question: when an ordinary business begins providing a service that functions like a financial product, where does conventional commerce end and regulated financial activity begin?
The latest CBN remarks suggest that answering that question will become increasingly important as embedded finance expands across Nigeria.
For now, consumers should not interpret the discussion as an announcement that instalment payments have been prohibited. Instead, the issue raised by the central bank concerns how such services should be classified, regulated and supervised, particularly when credit is provided outside traditional financial institutions.
Continue with Tokenpress
Open Tokenpress to comment, contact the creator or send a tip.